Many people understand cross-border logistics as simply delivering goods safely and on time from Point A to Point B. But in real cross-border cooperation, beyond the transportation chain, cross-border tax compliance and the dividends of tax treaties also directly affect the cost and smoothness of a business deal.
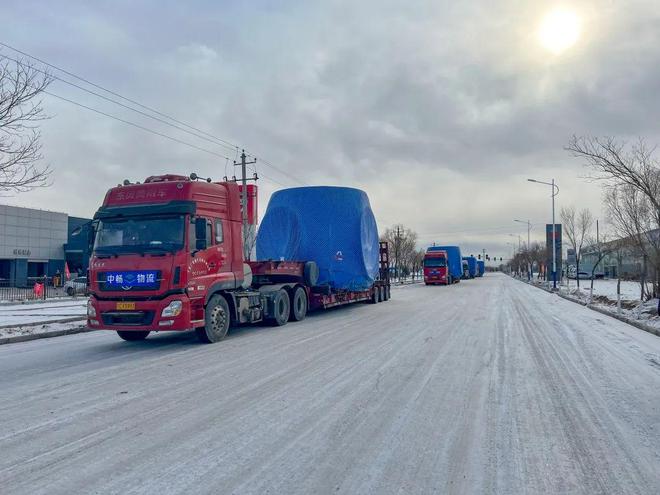
Recently, Judphone welcomed its first batch of Uzbekistan-bound transportation business, undertaking cross-border cargo transport from China to Uzbekistan. This is our first Uzbekistan project. During the process, we did not focus solely on logistics fulfillment itself — we simultaneously studied the cross-border tax rules of both countries and discovered the policy benefits brought by the double taxation avoidance treaty signed between China and Uzbekistan.
Key point:
Preferential treatment under a tax treaty does not take effect automatically. For international transportation business, a “Certificate of Chinese Tax Residency” must be provided as the basis for enterprise identity, and delivered to the Uzbek client for filing and review with the local tax authority before the preferential tax treatment under the treaty can be formally enjoyed.
Under Uzbekistan’s domestic tax law, foreign enterprises earning local transportation income are subject to a current withholding income tax rate of 6%. However, pursuant to the international transportation clause of the China-Uzbekistan tax treaty, profits derived by Chinese resident enterprises from the operation of international transportation by ship, aircraft, or road vehicle shall be taxable only in China. This means that, provided the Uzbek tax authority recognizes that the specific mode of transport falls within the treaty’s definition, the relevant transportation profits may be exempt from corresponding income tax in Uzbekistan, avoiding the additional tax burden caused by double taxation.
Merely obtaining the original “Certificate of Chinese Tax Residency” issued by the domestic tax authority is not enough. The Uzbek tax authority does not directly recognize the original domestic document; the certificate must also be notarized to form a notarial certificate. Only this notarized material can be accepted by the Uzbek tax authorities for tax treaty preference filing.
For this project, Judphone completed the entire processing procedure:
Reviewed the transportation contract and the full set of business documents, and verified the consistency of business information;
Applied to the competent tax authority through the electronic tax bureau for the issuance of the “Certificate of Chinese Tax Residency”; where the competent tax authority can determine tax residency status on its own, the certificate is issued within 7 working days;
Notarized the Certificate of Chinese Tax Residency to form a notarial certificate with cross-border validity;
Compiled the full set of notarized materials and delivered them to the Uzbek client for tax filing in Uzbekistan and application for tax treaty preferences.
Through this series of preliminary work, we help our cooperative clients compliantly enjoy the conveniences brought by the tax treaty between the two countries, avoid the risks of having taxes withheld locally and the cumbersome subsequent tax refund process, ensure smooth and full settlement of freight charges, and truly transform policy dividends into business advantages.
Friendly reminder: Whether the treaty preferences can actually be enjoyed is ultimately subject to the review results of the local tax authority in Uzbekistan; the specific applicable scope of the “international transportation” clause in the treaty with respect to modes of transport shall be determined by the Uzbek tax authority based on the actual business circumstances. We only assist in the processing and delivery of documents and do not constitute a tax approval commitment.
Many clients, when choosing a cross-border logistics partner, look first at freight rates, timeliness, and shipping space. But mature cross-border cooperation requires a partner who understands the rules and the hidden risks of cross-border operations.
The value of a logistics company has never been just about sending goods out. When business faces unfamiliar countries and such fragmented yet critical steps as cross-border taxation, document notarization, and overseas filing, we can identify risks in advance, streamline processes, and assist in preparing compliant materials, helping clients avoid pitfalls and detours.
From logistics solution design and cargo transportation fulfillment to cross-border document review and assistance in processing tax residency certificates, Judphone is committed to being a reliable partner in our clients’ cross-border cooperation. We do more than complete the spatial movement of goods — we support the smooth landing of every cross-border business with comprehensive service capabilities.
In the future, Judphone will continue to deepen its cultivation of the Central Asia cross-border logistics sector, continuously refine its comprehensive service capabilities, and provide more clients with stable, standardized, and worry-free cross-border supply chain solutions.
If you have cross-border transportation needs in Central Asia, or need consultation on cross-border documents and tax-related supporting matters, please contact us.
Cross-border cooperation is more than transportation; professional service makes every step more reassuring.
Contact phone:
Post time: Oct-16-2026